
Shopify fraud analysis · Order risk
Shopify Fraud Analysis: What It Can and Can't Tell You
By DisputeShield Team · Published 2026-08-31 · Last updated 2026-10-27
This article walks through Shopify fraud analysis as a workflow: what the native tools actually cover, how to read a risk signal without treating it as a verdict, a repeatable pre-fulfillment sequence with a small-team checklist, how to measure whether your policy works, and when adding an app is worth it.
The short answer for Shopify Payments merchants: build a short review policy, apply it to the same order every time, record what you decided and why, and check the fraud reports monthly to see whether your rules are catching the pattern you intended.
What Shopify fraud analysis is, and which orders get it
Shopify's fraud analysis is a built-in review tool that evaluates eligible online credit card orders for potential fraud before you ship them. On eligible orders it can show indicators and a low, medium, or high recommendation. The available detail depends on the order and the payment context, so treat what you see as a starting point for investigation rather than a complete picture of the customer.
Which orders receive a fraud recommendation matters, because it tells you where you have a safety net and where you do not. Test orders, free orders, gift card purchases, POS orders, B2B orders, and some subscription renewals may not receive a fraud recommendation at all. The practical takeaway: if Shopify does not analyze an order, your review policy has to account for that gap yourself, rather than assuming a missing flag means the order is safe.
Before you build a workflow, it helps to know what your store already has. Fraud analysis flags suspicious orders and helps you decide which ones to fulfill. It is available to stores that use Shopify Payments, and to stores using most third-party payment processors on the Grow, Advanced, or Shopify Plus plan. If you are on a third-party processor, check your plan before assuming fraud analysis is available.
How to read a risk signal without treating it as a verdict
The most useful question is not "Is this customer bad?" It is "What combination of facts makes this order unusual, and what action is proportionate?" One unfamiliar shipping address may be harmless. Several unusual details arriving together deserve more attention.
A "high risk" recommendation is an investigation cue. It is not proof that the customer is fraudulent, and it does not tell you a chargeback will follow. That distinction matters because a store can lose money in two directions: by fulfilling an order that later becomes a dispute, or by rejecting a genuine customer who would have reordered. A prevention workflow has to manage both.
Here is a compact way to read the signals you will see. The table maps a signal to a proportionate first action instead of an automatic verdict.
| Signal | What it reflects | Proportionate review action |
|---|---|---|
| High risk recommendation | Several signals Shopify's model detected together | Open the full risk details, read the indicators, compare the order to your store's normal pattern, then apply your policy: hold, verify, cancel, or fulfill |
| Proxy IP or masked location | The order came from a proxy service or an IP that hides its real location | Check whether the IP and location match the billing and shipping details; consider a hold and a customer confirmation if other signals also fire |
| Address mismatch | Billing and shipping addresses differ | Check customer history and whether the destination has appeared before; a gift or a move can explain the mismatch, so compare more than one signal before acting |
None of these facts proves fraud on its own. Customers send gifts, move house, travel, and use workplaces or family addresses. A careful process keeps the investigation focused on the order rather than making assumptions about the person.
Shopify's own review guidance points at concrete things you can check. Customer details worth a look include the IP address the order came from, the phone number on the order, and the email address, including whether the IP sits in a different area from where the customer claims to be, or belongs to a hosting company or proxy service. Shipping details matter too: a shipping address that differs from the billing address is a flagged pattern, though a legitimate customer sending a gift can produce the same mismatch. Several orders with different billing addresses and names all shipping to one destination is a stronger pattern.
Look for several related signals instead of reacting to one red indicator. Consider whether the order is normal for this particular store and product category. Separate payment risk from fulfillment risk, delivery risk, and customer-service risk. Avoid collecting or storing more personal information than the review requires.
What a high-risk order actually means, and what to do before fulfillment
When an order is flagged as high risk, it means Shopify's fraud analysis detected signals that its model associates with an elevated chance of fraud. That is a risk classification, not a determination about the customer. A high-risk order can still be a legitimate purchase: a traveler buying from a new location, a gift sender with a different billing address, or a customer using a VPN.
Shopify's chargeback guidance states that if fraud analysis reports an order as high risk, you can review the order and choose to cancel it, which can help you avoid chargebacks and inquiries on fraudulent transactions. The decision is yours, and it should follow your policy. The proportionate actions are:
- Hold when you need time to investigate and the order has not left your control. Give the hold an owner and a review deadline.
- Verify when the order looks legitimate but a detail needs confirmation, such as an address change or a shipping route you do not normally see. Contact the customer with a neutral explanation, and never ask for a full card number.
- Cancel when the order meets a documented rule, particularly where several strong signals appear together or a pattern has already cost the store money.
- Fulfill when the indicators are explainable, the order fits your normal pattern, and your records support proceeding.
Cancellation reduces your fulfillment exposure, but it does not close the door on a dispute. Canceling or voiding a high-risk order can help reduce the risk of a chargeback; it does not prevent the cardholder's bank from filing one. Authorization holds can also appear on the real cardholder's statement even when no payment is captured, and if the cardholder reports that hold as unauthorized, the bank can file a chargeback anyway.
"High risk" should not become a shortcut for automatic rejection. False positives cost real money: a lost sale, wasted support time, and a customer who may never return. If the store sells gifts, international products, limited releases, or high-value goods, unusual orders may be normal. The policy should account for those patterns and allow a human review where appropriate.
A repeatable pre-fulfillment review sequence for a small team
The gap between knowing what a signal means and acting consistently is where most small teams lose time. A fixed sequence fixes that. During a busy fulfillment window, write down the next decision you need to make before opening another tab: ship, hold, or cancel. That small habit keeps the review tied to an action instead of turning it into an endless search for certainty.
- Confirm the payment and fulfillment stage. A paid order waiting to be picked gives you a real review window. An order already handed to a carrier does not. Payment capture control changes this: if you are not on Shopify Payments, capturing payments manually lets you review high-risk orders before funds are collected, at the cost of an extra step in your fulfillment flow.
- Open the full Order risk section. Read the individual indicators, not just the summary color, and confirm whether the recommendation is low, medium, or high.
- Compare the order against its own context. Order amount and products, destination, delivery speed, customer history available to you, and whether the order looks like your normal pattern. Look for repeats: several orders in a short window, unusual quantities, or a run of failed payment attempts.
- Apply your written policy. The policy should state what triggers a hold, what triggers customer contact, and what triggers cancellation. Without it, two team members reviewing similar orders will reach different decisions, and the inconsistency is what creates disputes and angry customers.
- Record the decision before you act. Note the outcome, the reason, the owner, and the time. If a dispute opens weeks later, a recorded decision explains what you knew and why you chose it.
Shopify's own tools support parts of this loop. Order filters and automation options help teams manage risk at scale, and Flow can automatically flag, hold, or cancel orders matching patterns you define so every order does not need a manual pass. Automation is most useful when it applies a decision you have already made consistently. It is risky when it hides an unclear decision behind a rule.
A practical review checklist for a small team
Small stores rarely have a dedicated fraud analyst. The answer is not to create a complicated scoring model that nobody follows. A short checklist gives the owner, operations lead, or support teammate the same starting point each time.
- Confirm payment, fulfillment, and shipping status.
- Review Shopify's risk recommendation and the underlying indicators.
- Compare value, product type, address, shipping speed, and recent order history.
- Choose fulfill, hold, cancel, or refund according to the written policy.
- Record the decision, reason, owner, and timestamp.
Begin by confirming the order status and payment state. An order that has not been captured or fulfilled gives you a different set of options from an order already packed and handed to a carrier. Then open the full risk details and note which signals are actually present. Do not copy a generic explanation into the record if it does not describe this order.
Next, compare the order with the store's normal pattern. Is the value much higher than usual? Is the product easy to resell? Is the customer asking for a shipping route or speed the store does not normally see? Is the same email, address, or device pattern appearing across several recent orders? These questions help identify operational patterns without pretending that a merchant can prove intent from checkout data alone.
Finally, select an action and assign ownership. A hold without an owner is only a delayed problem. If someone needs to contact the customer, record who will do it and when the order should be reviewed again.
When to hold, fulfill, or cancel a flagged order
A three-way decision keeps the review proportionate.
Hold when you need time to investigate and the order has not left your control. This is common when an order is valuable, the customer is legitimate-looking but unfamiliar, or the team wants to confirm a delivery detail before shipping. A hold should have a purpose and a time limit. The policy might require a review within one business day, a customer confirmation for an address change, or a second look at several orders placed in a short period. The point is not to make every suspicious order wait indefinitely; it is to create a controlled decision window before inventory leaves the business.
Give the hold an owner and a review deadline, define who can release a hold, and release or cancel using the same policy that created it. If you contact the customer, keep the explanation neutral and never ask for a full card number or information your store does not need. A legitimate customer may be frustrated by a delay, so explain that the order is being reviewed without accusing them of wrongdoing.
For the deeper mechanics of a fulfillment hold, including how to place, track, and release one in Shopify, see our guide to Shopify order holds.
Fulfill when the indicators are explainable, the order fits your normal pattern, and your records support proceeding. A low or medium recommendation is not a guarantee of safety; it is one input among several.
Cancel or refundwhen the order meets a documented rule, particularly where several strong signals appear together or a pattern has already cost the store money. Cancellation may be the right business decision when it reduces exposure to a stolen-card chargeback, prevents a reshipping loss, or stops a repeated pattern your team has already documented. You should still follow Shopify's payment and refund procedures and communicate clearly with the customer.
A worked example: the expensive gift order
The following is a hypothetical scenario, not a customer outcome. A returning customer orders an expensive item three days before a holiday. Billing and shipping addresses differ, and the customer selects expedited delivery. Shopify raises the order for review.
Cancel immediately and you may lose a genuine gift purchase and a repeat buyer. Ship without looking and you may absorb the order value, fulfillment costs, and a dispute fee. A better review checks the available order history, whether the customer has shipped to that recipient before, the product, and any recent messages. If the same recipient address appears in past orders and the pattern is explainable, your policy might allow fulfillment. If there are also repeated failed payment attempts or an address change requested after purchase, a hold and a second review fit better.
The point is not certainty. It is a defensible, proportionate decision you can explain later.
The same reasoning applies to another common scenario, also hypothetical. A first-time customer places a high-value order and requests expedited shipping, and Shopify flags it for review. That is not a reason to accuse the customer or cancel automatically; it is a reason to pause, compare the signals, and follow the store's written policy. Start with the order stage: if payment is authorized but fulfillment has not started, you still have room to investigate. Check the order risk details, compare billing and shipping information, look at the requested shipping speed, and ask whether the basket is unusual for your store. If the review supports fulfillment, release the order and retain the decision record. If uncertainty remains, a short hold with a clear owner may be better than either automatic cancellation or shipping without review.
- Review before the shipping label is created.
- Use the least disruptive action that fits the evidence.
- Record why the decision was made and who approved it.
How to measure whether your review policy is working
Shopify provides fraud reports that turn your review policy into something you can actually check. All shops get three: acceptance rate (the percentage of total orders not flagged as high-risk), high-risk orders rate (the percentage of total orders flagged as high-risk), and canceled due to fraud (the value of orders canceled for fraud). Shops using Shopify Payments also get overall chargeback rate, chargeback rate (fraud), and chargeback amount (fraud).
Fraud reports cannot be customized, filtered, or edited, so plan your review around what each report already measures rather than building a custom view.
A monthly review that a small team can actually run:
- Pull the six reports and record the values.
- If your high-risk orders rate rose, check whether your order-value threshold or a specific rule is catching the pattern you intended or creating false positives.
- If canceled-due-to-fraud value rose while chargeback rate stayed flat, you may be rejecting more orders than the risk justifies.
- Change one variable at a time. If you adjust the order-value threshold, the shipping rule, and the customer-contact step together, you will not know which change produced the result.
Do not judge a risk policy only by the number of orders it blocks. Track the operational trade-off. At a minimum, review the number of orders scanned, held, canceled, released, and fulfilled after review. A policy that cancels everything may produce fewer suspicious shipments but also destroy conversion. A policy that never holds orders may preserve conversion while creating avoidable losses.
If the team can do so without exposing sensitive customer details, compare those actions with later refunds, delivery problems, and disputes. Look for trends by product, order value, shipping destination, and campaign rather than publishing individual customer stories. Start conservatively and document exceptions so the policy becomes more precise over time.
A repeatable order-review process is worth documenting properly rather than holding in one person's memory. Our shopify order risk review workflow for growing stores walks through owners, decision times, and improvement checks.
When an app adds value to your workflow
Native tools and an app are not competing answers. They solve different parts of the same problem. Ask three questions before adding anything:
- Where does your review break down? If the problem is that flagged orders sit unread during a busy week, you need a queue and an owner, not more signals. If the problem is that you have no way to apply your rules to orders you have already accepted, an app that acts on completed orders is the right shape.
- What decision do you want automated? Applying a rule you have already tested and documented to every matching order is a good automation candidate. Automating a judgment call you have not defined is not.
- What happens after a dispute opens? Prevention and response are separate jobs. If your evidence is scattered across email, admin, and a spreadsheet, an app that organizes it may save more time than one that only screens orders.
DisputeShield applies merchant-defined risk rules to completed orders and supports reviewing suspicious orders before fulfillment with configured hold, tag, or cancel actions. It uses Shopify's fraud analysis as an input alongside your rules rather than replacing it. When a dispute does open, it organizes evidence from available order, payment, fulfillment, policy, customer, and support records and prepares an evidence packet as a PDF, which you can review before submission or submit automatically when that is enabled in your settings. It also provides a dashboard for order-risk and dispute visibility and analytics for fraud pressure, disputes, risky orders, and revenue impact.
Understanding signals and applying rules are two different jobs. Shopify's fraud analysis tells you what a signal might mean; our guide to Shopify fraud filter apps explains how a rules engine turns that understanding into consistent hold, tag, or cancel decisions. And for the broader workflow that ties review, holds, and evidence together, see our practical Shopify fraud protection workflow.
Neither approach controls the issuing bank's decision, and neither can promise that every flagged order turns out to be fraudulent or every dispute goes your way.
Make it a policy, not a habit
A prevention workflow that lives in one person's head disappears when that person takes a week off. Write the policy down, give it an owner and a backup, set a review deadline for every hold, and check your fraud reports monthly against the pattern you meant to catch. Adjust one rule at a time and keep the records.
A useful policy fits on one page. It should explain which orders are automatically held, which can be canceled, who can override a rule, and what evidence must be recorded. Start with the store's actual losses and operational capacity. A business shipping low-cost items may tolerate more manual review than a business shipping expensive electronics, but neither should pretend every signal has the same meaning.
Review the policy after a small batch of decisions. Which held orders were released? Which cancellations were later regretted? Did the team miss orders because the rule was too narrow, or did it create too many interruptions? This feedback is more valuable than copying a competitor's threshold without knowing how its business operates.
For teams with multiple people, write examples beside the rule. "Hold orders over $X" is less useful than "Hold a first-time, high-value order with expedited shipping when the risk recommendation is high; an operations lead must review it before fulfillment." Examples reduce inconsistent judgment while leaving room for legitimate exceptions.
And record what happened before fulfillment. Note the risk signals reviewed, the decision, the person who made it, and the time of the action. Keep the record factual and avoid labeling a customer as fraudulent without evidence.
Frequently asked questions
Does Shopify fraud analysis prove an order is fraudulent? No. Shopify describes fraud analysis as information to help you investigate an order and decide which to fulfill. It provides indicators and a recommendation. It does not establish that a customer committed fraud.
Where do I see fraud analysis in Shopify? Open Orders, select the order, and review the Order risk section on the order detail page. Suspicious orders may also carry a warning marker in the orders list. Fraud reports live separately, under Analytics, where you can filter the Reports list by the Fraud category.
What is a high-risk order on Shopify? Shopify uses fraud analysis to provide indicators and, for eligible orders, a low, medium, or high-risk recommendation. Review the actual order details and signals in Shopify admin.
Should I automatically cancel every high-risk order? No. Apply a documented store policy. Depending on the facts, you may fulfill, hold for review, verify the order, cancel, or refund.
Turn fraud analysis into a repeatable review step
DisputeShield applies merchant-defined risk rules to completed orders, supports reviewing suspicious orders before fulfillment with hold, tag, or cancel actions, and uses Shopify's fraud analysis as one input alongside your rules. It keeps dispute evidence organized if a chargeback still opens.
Install DisputeShieldRelated articles
Shopify order risk · Store operations
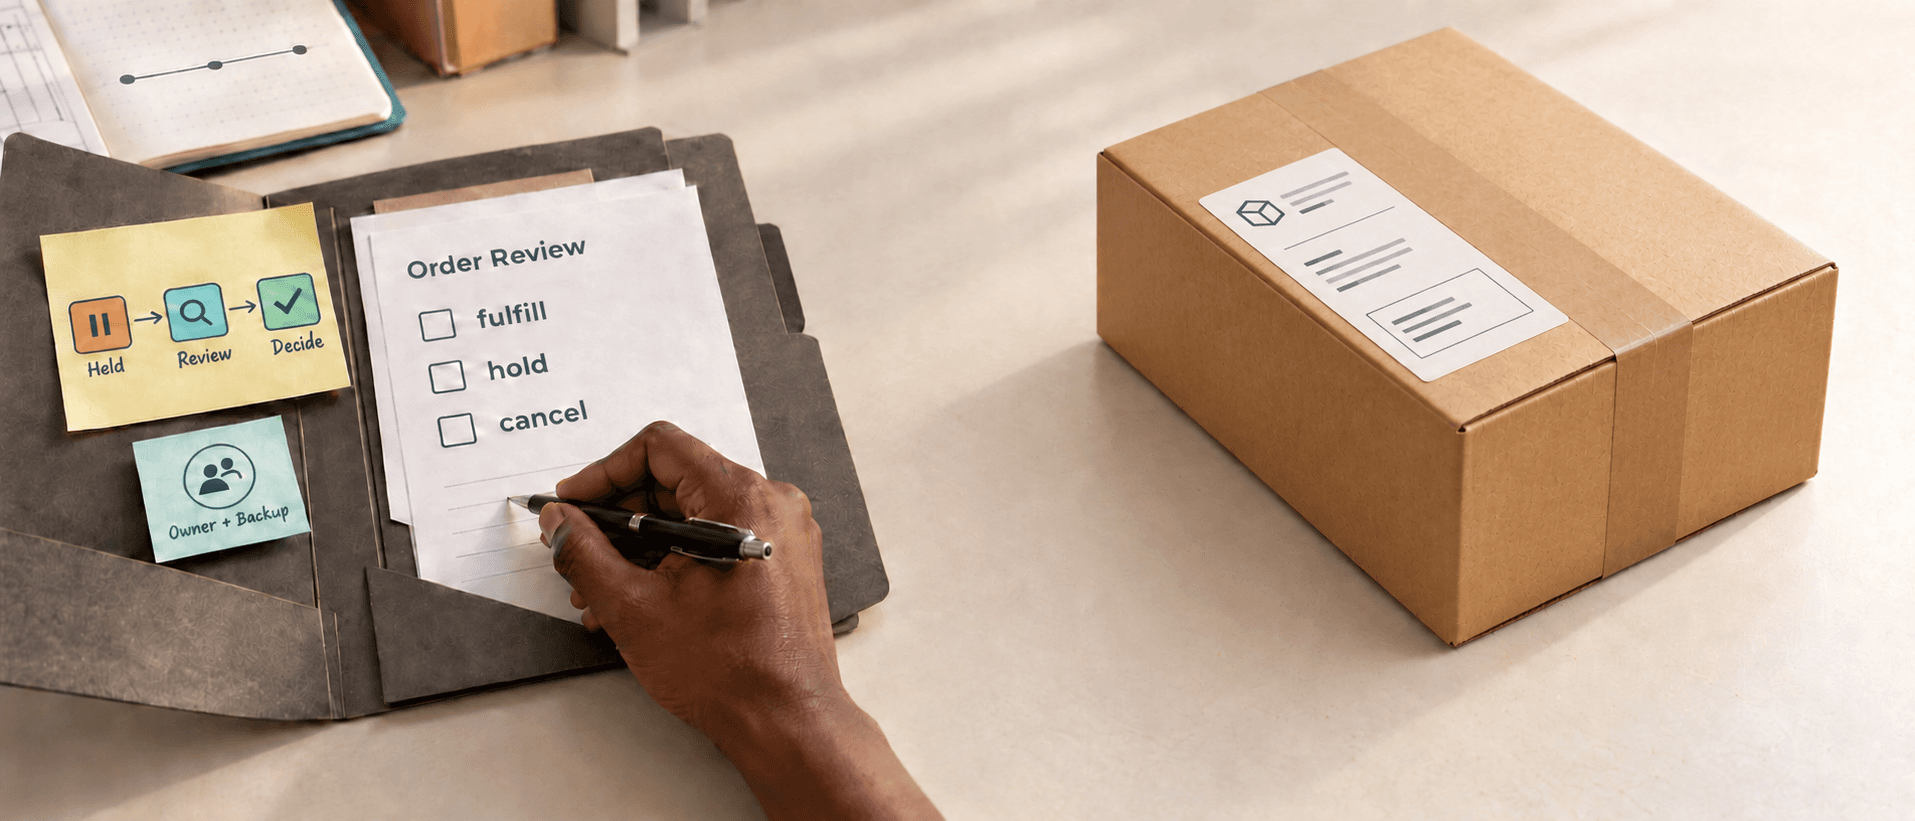
Shopify Order Risk Review Workflow for Growing Stores
Shopify order operations · Fraud prevention
Shopify Order Holds: When to Review, Fulfill, or Cancel a Risky Order
Shopify fraud prevention · Fraud filter apps